
Winter Luxury Shopping in Continental Europe
Emerging Destinations and Key Trends
As winter unfolded across Europe, luxury shopping remained vibrant, with major cities continuing to attract international shoppers. While Paris, Milan, and Madrid remained at the heart of the luxury scene, new cities also showed promising growth. Global Blue’s latest insights emerging evolutions in travel and Tax Freeending be haviors, equipping retailers with valuable data to refine their strategies.
Iconic Cities Reinforced Their Strength in Winter Luxury Shopping
During the winter period (December 2024–February 2025), traditional luxury hubs continued to dominate Tax Free Shopping sales:
- Paris reaffirmed its position as the world’s leading luxury shopping destination, accounting for 22% of total Tax Free sales in Continental Europe, with an impressive average spend per shopper of €2,660.
- Milan held strong with 9% of sales, benefiting from Italy’s global reputation for fashion and craftsmanship, and an average spend of €2,240.
- Madrid and Barcelona also performed well, contributing 8% and 5% of sales respectively. Madrid recorded a +25% year-over-year growth, signaling rising popularity among international shoppers.
- Rome captured 5% of sales, reinforcing its appeal as a cultural and shopping destination with a solid +20% growth and a €1,400 average spend.
Retailers in these core cities benefited from strong international demand, highlighting the importance of optimizing in-store experiences, VIP services, and refund solutions to capture high-spending tourists.
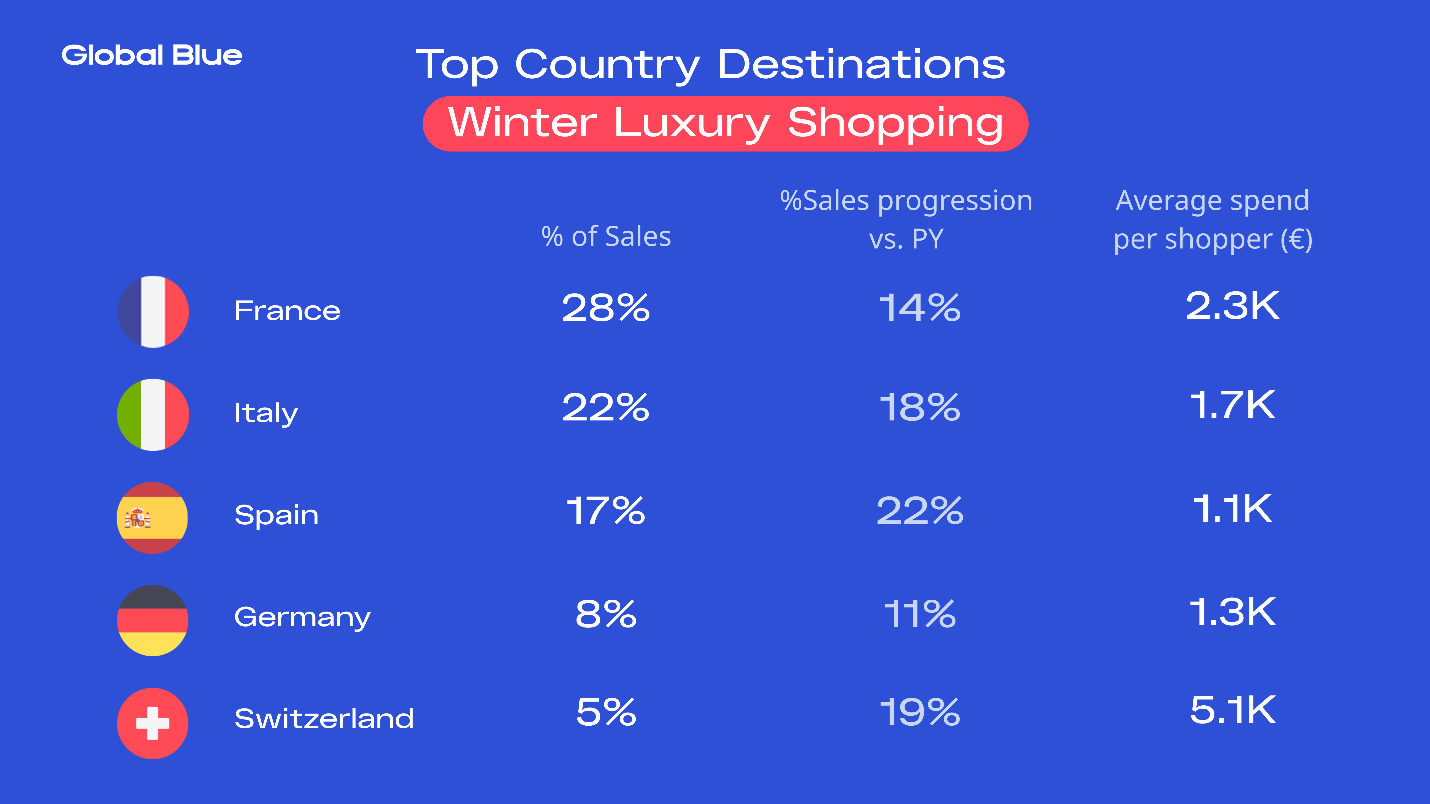
Top Country Destinations for Winter Luxury Tax Free Shopping
Several key markets in Continental Europe continued to attract international shoppers, reinforcing their role as luxury retail strongholds. Retailers in these regions benefited from strong international demand, reinforcing the need for optimized shopping experiences and strategic customer engagement.
Travelers Profiles and Spending Trends
Luxury Tax Free Shopping remained driven by distinct customer segments, each with unique purchasing behaviors:
- Ultra High Net-Worth Individuals (UHNWI): Represented 0.4% of shoppers but contributed 16% of total sales during the winter period1, with an exceptional average spend of €58,850.
- High Net-Worth Individuals (HNWI): Accounted for 1% of shoppers, contributing 17% of sales during the winter period1, with an average spend of €16,100.
- Affluent Shoppers: Made up 15% of shoppers, driving 39% of sales1, with an average spend of €4,160.
- Aspirational Shoppers: The largest segment (83% of shoppers), contributing 29% of total sales1, with an average spend of €550.
Retailers leveraging this segmentation could enhance their marketing efforts, tailoring strategies to engage each group effectively.

Cultural Influences on Retail Performance
Cultural events and seasonal festivities helped drive luxury spending during winter. Iconic celebrations such as Christmas markets in Paris, Milan, and Madrid, as well as special cultural programs in cities like Athens and Helsinki, attracted international tourists and boosted footfall in key retail districts.
Aligning retail activities with local cultural moments continues to be a key lever to enhance performance during peak travel seasons.
Partnering with Global Blue to Unlock Growth
As international shoppers explore more of Europe, retailers must elevate the in-store experience and streamline refund journeys.
Global Blue supports retailers across Europe by offering:
- Seamless digital refund journeys
- VIP Lounges for HNW clients
- Strategic Partnerships with leading digital wallets
- Advanced shopper insights and performance analytics
Ready to maximize your success in the evolving luxury market? Contact us to explore our full suite of solutions
1 The winter period: December 2024 to February 2025


